Novo's Michael Rangel on the Transformative Role of AI in Fintech
Michael Rangel, founder of fintech platform Novo, discusses how artificial intelligence (AI) has revolutionized his company. After nine years as CEO, he remains involved and supports Novo’s mission to empower small businesses. Key issues include the operational burden for banks serving small businesses, which AI can address through software solutions like compliance, fraud detection, and expense…
Key points
- Michael Rangel is the founder of fintech platform Novo
- Novo serves independent businesses with a range of financial tools
- AI has improved transaction labeling to over 97% accuracy
Michael Rangel, Founder of Novo
Unite.AI · 15 September 2026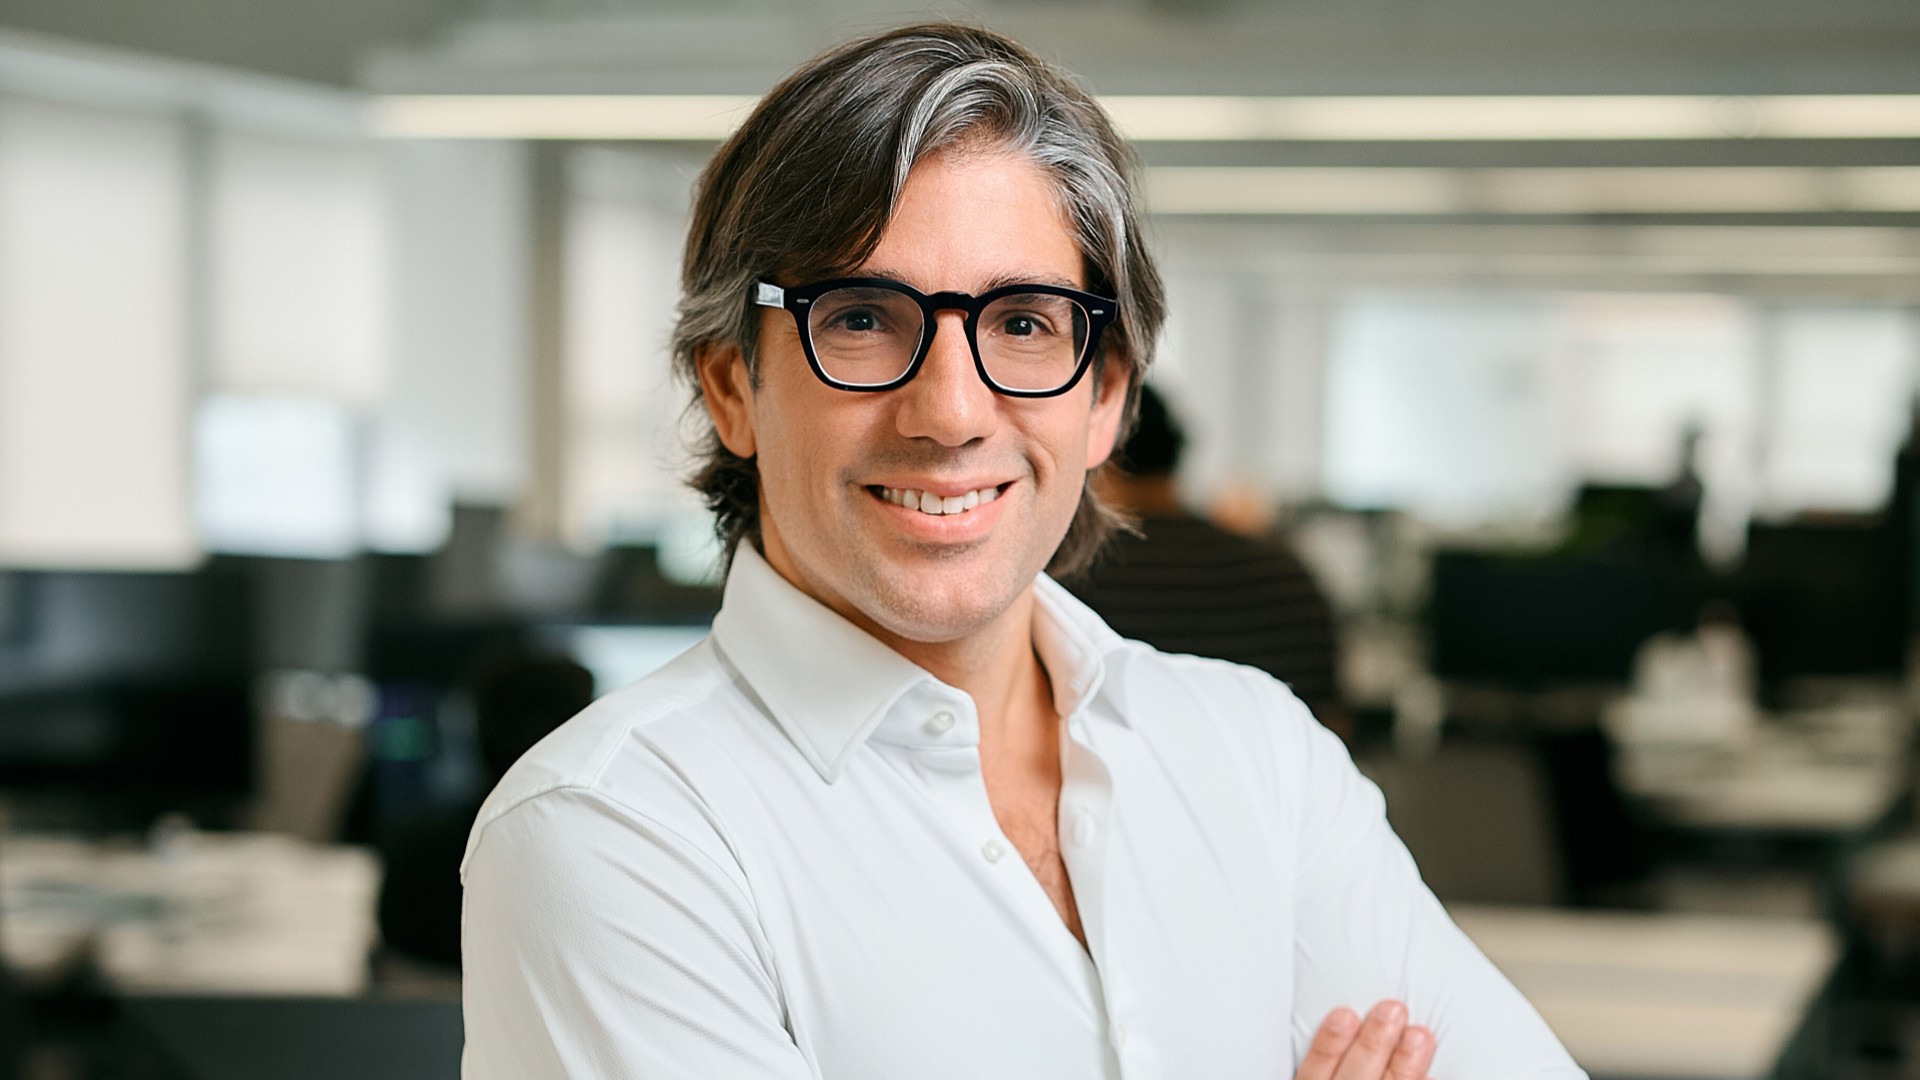
Michael Rangel, Founder of Novo, is a fintech entrepreneur who founded the company in 2016 and served as its CEO for more than nine years, helping transform Novo from an early-stage concept into a financial platform serving small businesses. During his tenure, Rangel worked across product development, fundraising, hiring, operations, partnerships, and go-to-market strategy, helping the company raise more than $170 million in funding. He stepped down as CEO in April 2025 but remains involved as Novo’s Founder and Board Member, supporting its long-term mission of empowering entrepreneurs and independent businesses. Before founding Novo, Rangel spent more than five years in trade administration and operations at Fairholme Capital Management, following an earlier operations role at Smith Barney.
Novo is a fintech platform designed specifically for independent businesses, entrepreneurs, freelancers, and small business owners, combining business checking with tools for payments, invoicing, expense management, cash-flow planning, lending, and business credit. The platform integrates with more than 40 business tools, including QuickBooks, Stripe, Shopify, Square, and Xero, helping businesses connect banking with accounting, payments, and operational workflows. Novo also incorporates AI powered by models from OpenAI, Anthropic, and Google to streamline processes such as onboarding and expense categorization. The company says its platform is trusted by more than 250,000 independent businesses. Novo itself is a fintech rather than a bank, with banking services and Federal Deposit Insurance Corporation (FDIC)-insured deposits provided through partner Middlesex Federal Savings.
You founded Novo in 2016 and spent nearly a decade building it around the financial needs of small businesses. Looking back at the problems you set out to solve then, which of them do you think AI can now address in ways that simply weren’t possible when you started the company?
AI can have a profound impact on how you operate a business and deliver value to customers. When we started Novo, one of the problems we wanted to solve was that a $1,000-a-year business, a $100,000-a-year business, and a $1 million-a-year business can create a surprisingly similar operational burden for a bank. You still have to support onboarding, compliance, fraud, security, transaction monitoring and customer service, regardless of how much revenue that customer generates for you. That meant banks had to build large operations teams to support customers who, individually, weren’t always that valuable to them.
Ten years ago, we believed software could help change that equation. AI is now taking that idea much further. A compliance specialist can use AI to summarize information, process documents and draft reports or responses, allowing one person to handle more than ten times the volume they could before. Our customer service teams can let AI handle routine questions so people can spend their time on the problems that actually require judgment. Fraud models can identify potential issues earlier and help us recover losses faster when something does go wrong. AI has given us a much better way to deliver on what Novo was built to do, which is provide a banking experience that works for businesses regardless of their size.
Small businesses have historically lacked access to the finance teams, analysts, and sophisticated software available to larger companies. How much can AI realistically close that resource gap, and where will human expertise remain essential?
AI is moving incredibly quickly, but the pace looks very different depending on where you sit. If you’re working in technology in San Francisco or New York, you probably have a very different experience of AI than a small-business owner who is simply trying to run their company.
A lot of the problems small businesses face are already within AI’s reach. The bigger challenge is that the technology is moving faster than people can learn how to use it. That’s why I’m interested in what companies like Anthropic are doing with products designed to give less technical users a starting point.
Human expertise isn’t going away, but AI can close the gap by making that expertise more accessible. I’ve seen products like April Tax make things that once required a lot of time and specialized knowledge much easier for a small business owner. We’re not at a point where AI can put your business on autopilot, but if you’ve ever lost a weekend preparing for tax filing, getting that time back matters.
Where are you seeing AI create the most tangible value for small-business owners today, particularly around cash-flow forecasting, expense management, budgeting, and day-to-day financial decision-making?
One of the most useful applications of AI we’ve built at Novo is actually something that sounds pretty simple, which is transaction labeling. Historically, getting these models to work well required a huge amount of training data, and even then you might get around 80% accuracy. That’s not good enough when you’re dealing with someone’s financial information because you still have to check everything.
By using a smaller amount of our own data, some model distillation techniques and frontier models when our systems aren’t confident, we’ve pushed that accuracy well above 97% and closer to 99% recently. Once you can accurately understand what every transaction represents, you can build much more useful financial tools on top of that data. It can power expense dashboards, basic FP&A and even help a business separate money for things like payroll and vendor payments so they don’t accidentally spend it elsewhere.
What’s interesting is that LLMs are surprisingly good at classification and clustering. That means we can take a business’s transactions and start building a personalized view of its finances without the engineering complexity that used to be required. For our customer base, the capabilities of today’s AI are actually ahead of the complexity of the problems we’re trying to solve. That’s a pretty exciting place to be.
One of the promises of AI is moving financial software from simply showing business owners what happened to proactively telling them what they should do next. What does a genuinely intelligent financial platform look like in practice?
The best banking experience you can have is still talking to someone at your bank who knows everything about your business. They understand your history, what you’re trying to accomplish and what you might need next. Software has always been an enabler of that relationship, but it hasn’t replaced it.
For me, a genuinely intelligent financial platform starts to feel like you’ve reduced the number of people you need in the room to manage your business. You should be able to ask a question, get an answer, see the right information, and receive useful guidance without having to figure out where to look for it yourself. The important part is that you trust the answer.
At Novo, we sometimes say we’re competing with the sidewalk. Going to a banking advisor is still a great experience. There’s no app to navigate, someone knows you and they can guide you based on your business. What AI gives us is the chance to bring some of that experience to an underserved group of businesses at a scale that wasn’t possible before. For our customers, that opportunity is finally within reach.
Could AI eventually function as a kind of virtual Chief Financial Officer for a small business, continuously monitoring finances, identifying risks, and recommending actions? What capabilities would need to mature before entrepreneurs could trust such a system?
Yes, and I say that confidently because it’s something we’re already building. Earlier this year, we released our AI Agent infrastructure specifically to move toward that vision.
The hard part isn’t getting a model to answer a question. It’s building something people can trust with their financial lives. We learned that firsthand. Our first beta cohort was good, but it wasn’t good enough for us to say the experience wouldn’t eventually break someone’s trust. So we kept pushing, improving how the system learns, how specialized agents work together, and how they use the information and tools available to them.
What we’ve built is essentially a banking-specific system of agents, with different agents handling things like transactions, fraud, cards and ACH, each with their own tools and knowledge. It took a lot of work to get there, but the results are now genuinely good. We don’t want to rush something like this just because AI is having a moment. That’s unfair to the customer. But for businesses at the size we serve, I believe that moment has arrived, and that’s incredibly exciting.
Access to capital remains one of the biggest challenges for small businesses. How could AI change underwriting and lending, and could alternative data allow financial institutions to evaluate businesses that traditional credit models tend to overlook?
This is one area where I think the conversation gets confused. It’s not really about AI. It’s about fairness and understanding what these models are actually capable of.
You should never use a frontier language model as the model making a credit decision. LLMs are non-deterministic, meaning the same inputs can produce different outputs. Traditional machine-learning models used for credit decisions are deterministic, so the same inputs produce the same result. That distinction matters enormously when you’re deciding who gets credit. You need to know what factors are driving the decision, test for bias, and be able to correct problems when they appear.
AI can absolutely help us build better models for understanding risk, and we do that extremely well at Novo. But I don’t think AI alone solves the bigger problem of small-business access to capital. A lot of that problem comes from the regulatory environment created by the Basel framework, which changed the economics of small-business lending for banks and made them less willing to take those risks.
We always say small businesses are the backbone of the economy, but we have built a financial system around them where many of the decisions affecting their ability to survive are made in rooms they don’t get to speak in. That’s a much bigger problem than whether we have a better AI model.
AI is also becoming increasingly important in fraud detection and financial security. How can financial platforms use AI to identify suspicious activity without creating excessive false positives or making legitimate transactions more difficult for small businesses?
AI is particularly useful for spotting things that don’t look right. Language models are surprisingly good at classification and clustering, which means you can use them to identify unusual behavior at a relatively low cost.
The important distinction is that I wouldn’t use a non-deterministic model to make the final decision. I would use it to raise a flag and then have a deterministic model make the decision. That’s how we’ve approached fraud at Novo.
We also work with companies like Sardine, which can bring patterns from a much broader set of financial institutions into our models. They can help us identify things like credentials that have previously been associated with fraud or behaviors that look like automated activity. We’ve built a strong fraud operation around that combination of technology and expertise. Security is always an arms race, but AI is giving us better tools to stay ahead of it.
Financial AI systems may have access to extremely sensitive information about a company’s revenues, expenses, customers, and financial health. What safeguards should entrepreneurs expect around data privacy, security, and the use of their financial data to train AI models?
There are a few layers to this, starting with the policies and terms of the models you’re using. The major frontier model providers have enterprise and API offerings where customer data isn’t used to train their models, but there’s still an important distinction between using a model through an API and using it through a consumer-facing application where your conversation history is stored.
There is also a question of how much information you actually want to give an AI system. At Novo, we’ve designed our agents so customers can make that choice. You might want an agent to answer questions using only our banking knowledge, or simply point you to where information lives in the app, or you might be comfortable giving it more of your financial data because that produces a better answer.
We also put systems between customer data and the models that can automatically remove sensitive information such as EINs and Social Security numbers, and we repeatedly test our systems to make sure they don’t expose information they shouldn’t. That’s what makes building good AI difficult. It’s not just about making the model smart. You have to build the safeguards around it and keep testing them.
There is enormous enthusiasm around AI in fintech right now. Which applications do you believe are genuinely transformative for small businesses, and where do you think the industry is currently overhyping what AI can deliver?
There should be enthusiasm for AI in every industry. We’ve seen this movie before. The internet changed how we distributed software, browsers changed how we accessed it, cloud computing changed how we deployed it, and mobile changed where we could use it. AI is now changing how we experience software.
What I find most interesting is that we’re also changing the language of software itself. People can increasingly build software by describing what they want in natural language instead of learning JavaScript or Python. For decades, that technical knowledge was one of the things that kept software development behind a gate. That gate is starting to come down, which is part of why companies like Lovable and Replit have grown so quickly.
At the same time, I think we’re still very early. A lot of the hype comes from people in Silicon Valley who are experiencing AI at a completely different pace than everyone else. The companies getting real value from it aren’t treating it like magic. They’re figuring out what it can actually do and applying it to problems where it works.
We’re still at the beginning of this. When you compare AI adoption with the early adoption curves of the internet and mobile, it’s incredibly early. So I think dismissing AI because today’s technology doesn’t live up to some of the hype would be like looking at the early internet and deciding it was a fad.
Looking ahead, how do you think AI will reshape small-business banking itself? Could we eventually move from today’s model of accounts, dashboards, and financial tools toward autonomous financial platforms that actively manage much of a company’s financial operations on the owner’s behalf?
This is the vision we’re building at Novo. Fundamentally, we want to recreate the experience of having a great banking advisor on your phone. You should be able to ask a question and get an answer, have a chart or report generated when you need it, hear about credit when the timing is right, discover insurance as your business grows and even learn about grants or tax changes that could benefit you.
The innovation isn’t simply having AI do things for you. It’s getting AI to do those things well enough that you actually trust it. That’s much harder than it sounds, and I think trust is becoming a feature of the product itself.
AI can hold far more information in context than a person can, but it can’t replace the human relationships that actually drive businesses forward. People take the risks, build the relationships and create the opportunities that move the economy. That’s why our measure of success at Novo isn’t getting you to spend more time in our app. It’s the opposite. We want you to spend as little time there as possible and accomplish more in those few minutes than you could before.
Thank you for the great interview, readers who wish to learn more should visit Novo.
This text was published by Unite.AI and written by Antoine Tardif, CEO & Founder of Unite.AI. It is reproduced here with attribution so you can read it in full; the rights remain with the publisher. Read it at the source ↗
The headline, key points and digest above were generated by Digest AI's editorial model from the linked sources. Automated summaries can contain errors: the sources are the record. Spotted a mistake? Tell us.
More in Generative AI & Models
All →- Apple launches iOS 27 and Siri AI with waitlist and EU restrictions · 15 src
- TypeSafe AI unveils Jev, a frontier model up to 400× cheaper and 200× faster · 1 src
- OpenAI's GPT-6 Astra Drives Enterprise Spend Ahead of Anthropic · 2 src
- Google DeepMind launches Gemini 3.8 Live and 3.8 Live Extended Thinking models · 3 src
- No Big Deal: A Boring AI-Generated Sitcom · 1 src
Comments
via GitHub Discussions